On November 15, 2024, more than 55,000 Canada Post workers went on strike, two weeks before Black Friday. Mail delivery across the country stopped for 32 days, until the federal government ordered an end to the stoppage on December 17. Small firms that billed customers by post and waited for checks in return found their incoming payments stuck in the same backlog as their outgoing parcels.
Cash Flow During the 2024 Mail Stoppage
The Canadian Federation of Independent Business estimated that small business firms were losing $100 million a day during the strike, with total damage of $1.6 billion by mid-December. In a statement on December 13, 2024, the federation said millions of dollars in payments were frozen in the mail and that many businesses were waiting on check payments from their business customers. Nearly three-quarters of small firms told the federation they planned to reduce their dependence on Canada Post afterward.
Mail stopped again in 2025. In May of that year an Industrial Inquiry Commission concluded that Canada Post was effectively insolvent, and in the fall a countrywide strike halted all deliveries for more than two weeks before the union switched to rotating strikes in October.
Card Use Across Canada
Payments Canada counted 22.5 billion retail payment transactions worth $12.2 trillion in 2024. Credit cards accounted for 33% of those transactions by volume and debit cards for 30%, and the number of credit cards in circulation reached 112 million. Contactless payments made up 58% of all transactions. Checks made up 2% of payment volume, and their total value fell 24% between 2020 and 2024.
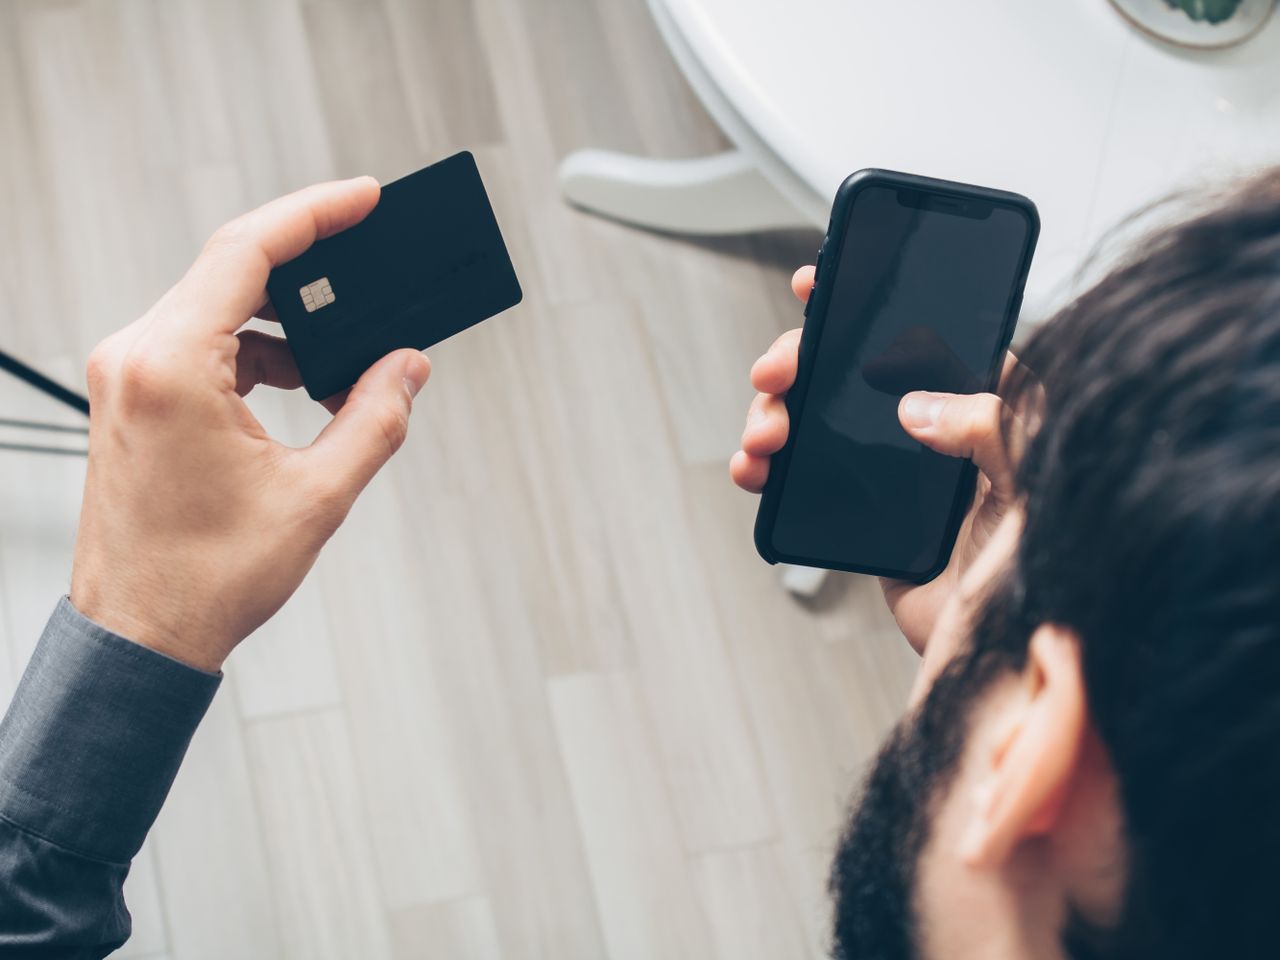
Most Canadian customers therefore have a credit card on hand when they call a business. Taking card details over the phone lets a firm collect payment when the order is placed, instead of depending on a check moving through a postal system it does not control.
Debit Cards on a Phone Order
The Interac network, which handles most debit purchases at a store counter, is built for card-present payments, and its Interac Online service for web purchases was discontinued on October 31, 2024. A plain Interac debit card generally cannot be used for a phone order.
Many Canadian banks now issue debit cards that carry Visa Debit or Debit Mastercard alongside Interac. Those cards still use Interac in stores, and they use the Visa or Mastercard network for online and phone purchases and for purchases made abroad. A virtual terminal for credit card processing accepts these co-badged debit cards in the same way it accepts a credit card, because the charge is processed on the Visa or Mastercard network.
Customers without a co-badged card can pay by Interac e-Transfer, a bank transfer sent to the business’s email address. Online transfers made up 7% of Canadian payment volume in 2024, and their volume grew 175% from 2020 to 2024. These transfers are sent by email, which makes them a target. In July 2025, an Oshawa, Ontario, woman’s $3,500 e-Transfer was intercepted and redirected to a different account. Turning on autodeposit sends incoming e-Transfers straight to the business’s bank account without a security question.
Lower Credit Rates for Small Merchants
On October 19, 2024, Visa and Mastercard lowered the interchange fees paid by qualifying small businesses under agreements with the federal government. Firms with annual Visa sales below $300,000 or annual Mastercard sales below $175,000 qualify. For in-store sales, domestic consumer credit interchange fell to an annual weighted average of 0.95%, a reduction of up to 27%. Online rates were reduced by 10 basis points. When the terms were first announced in 2023, the average interchange fee on a Canadian Visa credit card was 1.4%, and the agreement brought the in-store average interchange fee below 1% for qualifying merchants. The government estimated the savings for eligible small businesses at about $1 billion over five years.
A phone order keyed into a browser is not an in-store transaction, so the 0.95% in-store average does not apply to it. A business that splits its card sales between a counter and the phone will see two different rates on its statement, and the gap matters when it estimates the cost of moving more customers to phone payments.
Surcharge Rules on Phone Sales
Since October 6, 2022, Visa and Mastercard have allowed merchants in Canada to add a surcharge to credit card sales, capped at 2.4%. A merchant must notify its card brands and its processor 30 days before it begins surcharging, may not charge more than its actual cost of accepting the card, and must tell the customer about the fee before the sale is completed. When the rules changed, a Canadian Federation of Independent Business survey found that 19% of small businesses were considering a surcharge and 26% would add surcharges if their competitors or suppliers did, with firms that sell to other businesses the most likely to do so.
On a phone order, that disclosure has to happen during the call, before the card is keyed. Quebec is the exception, since the province’s Consumer Protection Act forbids credit card surcharges, and a business with customers in Quebec needs to know where each caller lives before adding the fee.
Contract Rights for Merchants
A revised Code of Conduct for the Payment Card Industry in Canada took effect on October 30, 2024, with full enforcement by April 30, 2025, under the oversight of the Financial Consumer Agency of Canada. Providers must give at least 90 days’ notice of a new fee or a rate increase. After such a notice, the merchant can cancel its agreement without penalty within 90 days, and the same right applies when a processor does not pass on a cut in interchange rates.
Monthly statements have to list the effective rate for each type of card along with all fees and transaction volumes, which lets an owner see what phone orders cost compared with counter sales. Fixed-term agreements can only be extended in six-month intervals, so a small business is not locked into a long automatic renewal.
The Next Mail Stoppage
The 32 days of November and December 2024 showed how much of a small firm’s cash can depend on envelopes moving through one national carrier. A business that now takes card payments by phone collects that money during the call, and its revenue keeps arriving the next time the mail stops.