Canadian shoppers crossing the U.S. border for Thanksgiving need to understand personal exemptions, 15%, 25% and 50% surtaxes, taxes and origin rules
Personal exemptions still apply, but some U.S.-origin purchases can face a 15%, 25% or 50% surtax when Canadians return home
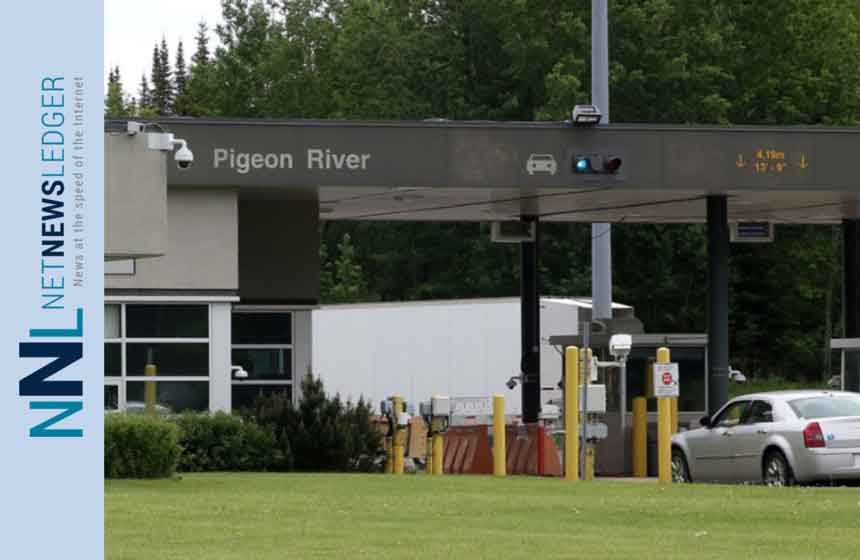
THUNDER BAY — Some Canadians will cross the border for shopping during the Thanksgiving long weekend, which runs from October 10 to 12, 2026.
The Canada Border Services Agency (CBSA) says new counter-tariffs apply to certain goods originating in the United States. The surtaxes took effect September 8 and are set at 15%, 25% or 50%, depending on the product.
The rules do not mean every item bought in the United States will automatically be charged a tariff. Personal exemptions, product classifications and country-of-origin rules all matter.
The first question: how long were you outside Canada?
CBSA personal exemptions depend on the length of the trip.
Same-day trips: less than 24 hours
There is no personal exemption for a same-day shopping trip.
That means taxable goods brought back into Canada may be subject to applicable customs duties, GST or HST, and the new surtax if the product is on the counter-tariff list.
For example, if a shopper buys a C$200 U.S.-origin product subject to a 25% surtax, the surtax alone would be approximately C$50. GST or HST is then calculated on the value that includes the surtax. Other duties may also apply.
Trips of more than 24 hours
Travellers may claim a personal exemption of up to C$200.
The goods must be for personal or household use, be with the traveller when returning and be declared to CBSA. Alcohol and tobacco are not included in the 24-hour exemption.
If the value exceeds C$200, CBSA says the exemption cannot be claimed and duties and taxes apply to the full value of the imported goods.
Trips of more than 48 hours
Travellers may claim an exemption of up to C$800.
If the value is more than C$800, duties, taxes and applicable surtaxes generally apply to the amount over the exemption.
For example, if a traveller returns after more than 48 hours with C$1,000 worth of U.S.-origin goods subject to a 25% surtax, the surtax on the C$200 overage would be approximately C$50, before GST or HST and any other applicable charges.
The calculation can be different for specific products, so travellers should use the CBSA estimator and keep receipts.
What products are affected?
Canada’s counter-tariffs cover selected U.S.-origin products, including goods in sectors such as:
- Steel and some metal products;
- Dairy and food products;
- Appliances;
- Agricultural equipment;
- Pulp and paper;
- Electronics; and
- Other products identified in the federal tariff schedules.
The rate is based on the specific tariff classification. Two products that look similar in a store may have different tariff treatment.
The CBSA says the surtax is calculated as a percentage of the “value for duty” before GST or HST. The surtax is then added to the value used to calculate applicable taxes.
Where a product was made matters
The tariff is based on where the goods were made, not simply where they were purchased.
A Canadian shopper could buy an item at an American retailer that was manufactured in Mexico, China or another country. If the shopper can show that the product was not made in the United States, the Canadian counter-tariff may not apply.
On the other hand, a product bought outside the United States can still be subject to the surtax if it is clearly marked as made in, produced in or originating in the United States. The burden of proving origin rests with the person bringing the goods into Canada.
Travellers should keep receipts, packaging and country-of-origin information where possible.
Alcohol and tobacco have separate rules
CBSA rules for alcohol and tobacco continue to apply in addition to the new tariff measures.
After an absence of 48 hours or more, a traveller may generally bring in one of the following duty- and tax-free amounts:
- Up to 1.5 litres of wine;
- Up to 1.14 litres of spirits; or
- Up to 8.5 litres of beer or ale.
Provincial limits and minimum-age rules also apply. In Ontario, travellers should confirm requirements before returning, especially if they are bringing back quantities beyond the personal exemption.
Alcohol bought in the United States must be declared. Travellers should not assume that a purchase is covered simply because it is for personal use.
Online purchases and shipped goods
The same tariff issue can arise when goods are shipped to Canada by courier or mail.
CBSA’s Customs Notice 26-23 says the surtax can apply to commercial and casual imports, including shipments that fall below certain low-value thresholds. The notice also says surtaxes can apply to goods imported from another country if they are marked as U.S.-origin.
Courier companies may also charge brokerage, handling and processing fees. Those fees are separate from the government tariff and taxes.
What this means for Northwestern Ontario shoppers
For residents of Thunder Bay and Northwestern Ontario, a cross-border shopping trip may still make financial sense for selected items. But the calculation is no longer just the U.S. sale price converted into Canadian dollars.
Shoppers should also consider:
- The exchange rate;
- The length of time outside Canada;
- The personal exemption available;
- Whether the item is U.S.-origin;
- Whether it appears on Canada’s surtax list;
- GST or HST;
- Provincial alcohol rules; and
- Courier or brokerage charges for shipped goods.
A sale price can disappear quickly if a product is subject to a 25% or 50% surtax and the traveller has no personal exemption.
Declare everything
Travellers are required to declare the goods they are bringing into Canada. Failing to declare an item can lead to seizure, penalties or other enforcement action.
The safest approach is to keep all receipts together, know the country of origin and tell the CBSA officer exactly what was purchased.
The new surtaxes do not ban Canadians from shopping in the United States. They do mean that cross-border shoppers must calculate the full landed cost before deciding whether the trip is worthwhile.